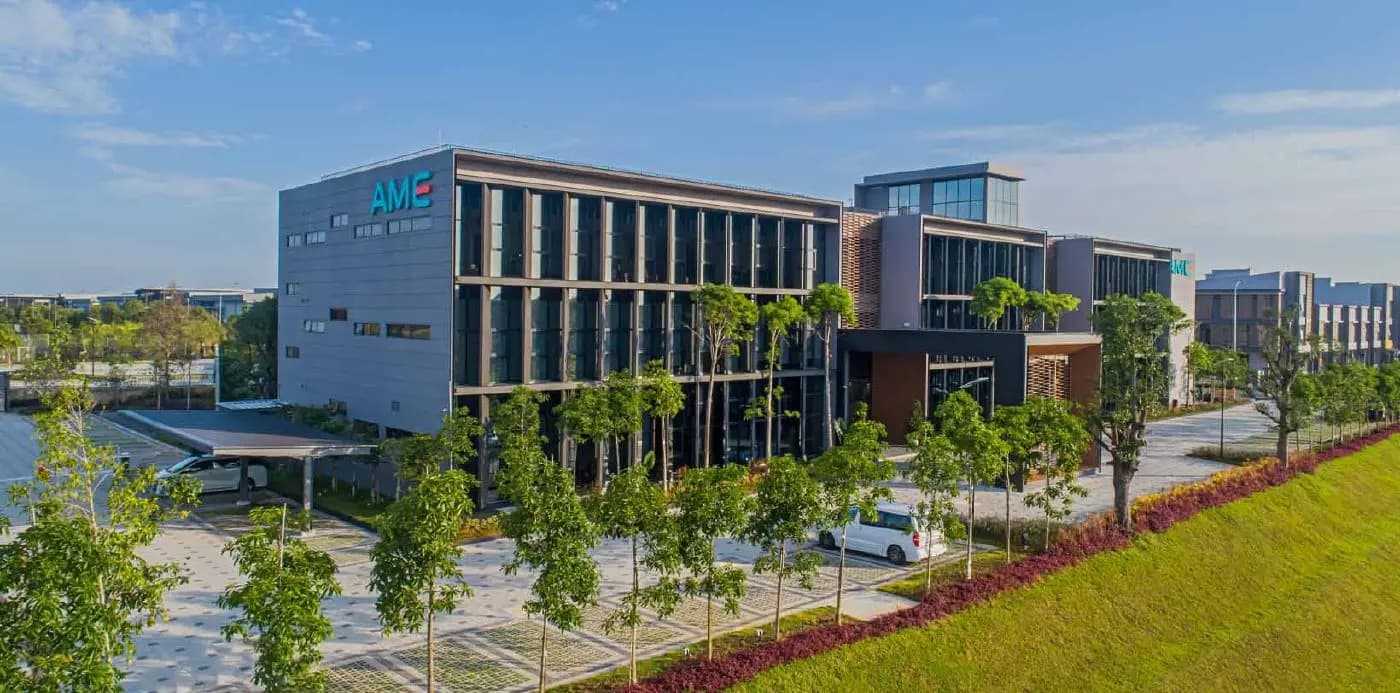
Stronger FY27 earnings for AME Reit on rental reversions, says HLIB
KUALA LUMPUR: AME Real Estate Investment Trust (AME Reit) is expected to see stronger earnings in financial year 2027 (FY27), driven by rental reversions at Senai Airport City (SAC) and Indahpura, alongside initial contributions from the i-Park SAC 34 acquisition.
While general portfolio guidance points to renewal rental reversions of about 11 to 13 per cent (capped at around 20 per cent), Hong Leong Investment Bank Bhd (HLIB) said AME Reit's recent track record suggests stronger potential in SAC.
It noted that SAC's passing rents of RM1.85 to RM1.90 per square foot (psf) remained more than 35 per cent below current market rates of above RM2.50 psf.
"Management's track record in securing about 40 per cent reversions recently on replacement tenants confirms the prevalence of this market gap, signalling significant organic upside for upcoming lease expirations in the segment.
"Top-line growth in FY27 will be further underpinned by a nine-month inorganic revenue contribution from the i-Park SAC 34 acquisition (completed June 30, 2026), which also enjoys a built-in 3 per cent annual step-up through FY30," it said.
Meanwhile, HLIB said the Indahpura cluster entered AME Reit's listing structurally under-rented due to legacy pre-initial public offering contracts, creating a multi-year catch-up runway that management is actively unlocking.
Given Indahpura's deeper discount to SAC market rates, it said rental reversions have been noticeably stronger.
"A recent renewal with an existing tenant achieved a rental uplift of more than 30 per cent, exceeding comparable SAC renewals of 11 to 20 per cent and narrowing the rental gap to about 10 sen to 15 sen psf.
"Management intends to replicate this strategy across upcoming expiries, and with tenant engagement typically beginning six to nine months ahead of expiration, the associated reversion upside is still to come, in our view," it said.
Overall, HLIB said defensive master-leased dormitories safeguard baseline yields, leaving the i-Park @ SAC build-to-lease project to unlock the next earnings inflection from FY29.
"Following our coverage resumption, we introduce our FY27 to FY29 earnings forecasts. We maintain a "Buy" recommendation on AME Reit with a target price of RM1.67," it added.
Source published at: 23 Sep 2026, 4:34 AM
Findhouse published at: 28 Oct 2026, 12:12 PM